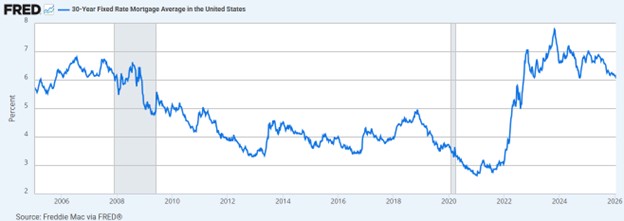
Over the past five years, we have experienced one of the most dramatic interest rate cycles in modern real estate history. Mortgage rates moved from the lowest levels ever recorded in late 2020 to late 2021 to the highest they’ve been in more than 35 years in 2023 and early 2024, and now, once again, they are trending lower.
For many homeowners considering selling their current home and buying another, this volatility has led to hesitation. A common question we hear is: Should I wait for rates to drop further before selling and buying a new home?
It’s a fair question, but the answer may surprise you.
Today’s Rates Are Already the Lowest They’ve Been in Years
While today’s rates may still feel high compared to the historic lows of 2020 and 2021, it’s important to put the current market into context. Those historic sub-3% rates were driven by extraordinary economic conditions due to the pandemic.
By contrast, today’s rates:
- Are significantly lower than their recent peak
- Represent the lowest levels we’ve seen since 2022
- Are expected to continue declining, with some forecasts projecting as much as a one-percentage-point drop over the course of this year
As you can see from the chart below, rates in 2008 were exactly where we are today, and that low sub-3% rate is a complete anomaly. What matters most, however, is not where rates were- but where they’re headed.
Click to enlarge – source
Why Falling Rates Can Benefit Sellers Before They Reach the Bottom
When interest rates decline, the housing market doesn’t wait for them to hit their lowest point. Buyer behavior shifts early.
As rates move downward:
- Buyer confidence improves
- Monthly payments become more manageable, and affordability is less constrained
- More buyers re-enter the market
Historically, this early phase of declining rates often brings increased demand before a surge in new listings. That creates a window where sellers can benefit from improved buyer activity while facing less competition than they might later.
The Rate You Have vs. The Asset You Own
Another major factor holding homeowners back is the so-called the “golden handcuffs” or the “lock-in effect.” Many homeowners who are would-be sellers are understandably reluctant to give up the ultra-low mortgage rates they secured years ago.
But it’s important to remember:
- Your home is a long-term asset, not just a low mortgage rate
- Life changes, whether that means downsizing, relocating, or upgrading, don’t always align with perfect interest rate conditions
- Buyers over the last few years have adapted through creative financing options such as mortgage rate buy-downs, adjustable rate mortgages, and other long-term planning
- There is always the option to refinance in the future when rates fall lower than the rate you currently have locked in.
Focusing solely on the rate can sometimes overshadow broader financial and lifestyle goals.
A Smarter Approach: Positioning, Not Timing
The most successful sellers aren’t waiting for perfect conditions. They’re preparing early to list in the winter, which is a surefire way to sell for as much as possible. Pricing strategically and positioning their homes to take advantage of improving market momentum so that they can also turn around and buy the next perfect home for where they are in life now.
If you’re considering selling, the better question may not be “What will rates do next?”
It may be “How can I position my home to succeed as the market continues to improve?”
Understanding today’s conditions and acting with a clear strategy can make all the difference. Contact me today to get started!